Securing Prime London Real Estate Through Off-Market Freehold Aggregations
The prime central London residential market has long been defined by its scarcity of institutional-scale assets, particularly within ultra-prime enclaves like Knightsbridge. For ambitious young business leaders and international family offices looking to deploy capital into trophy real estate, securing a controlling interest in a historic square is an exceedingly rare opportunity. Offering a unique entry point into the Royal Borough of Kensington and Chelsea (RBKC), this prime London portfolio represents a once-in-a-cycle off-market freehold aggregation designed for sophisticated capital allocators.
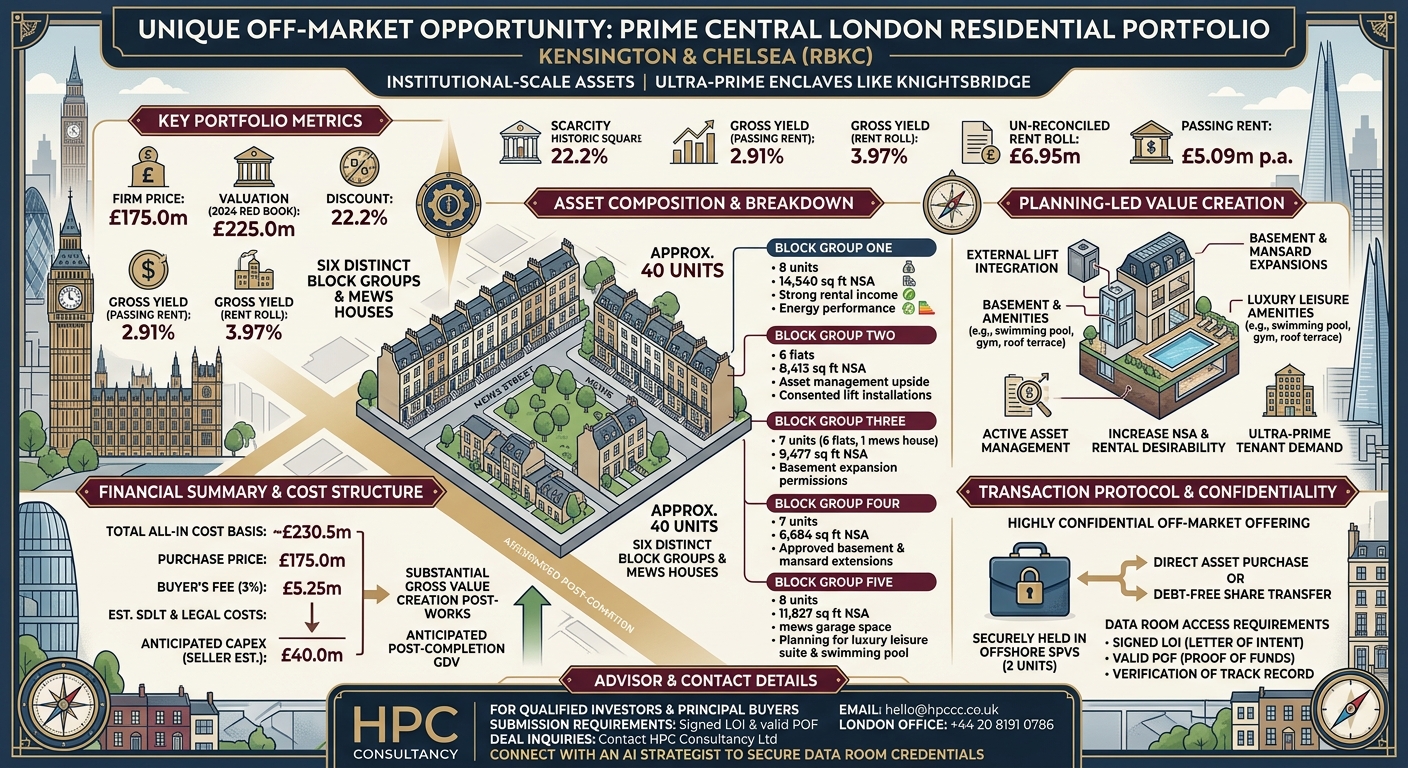
Brought to market via confidential channels, this exclusive portfolio opportunity spans six distinct block groups alongside complementary mews houses. With a vendor-stated firm price of £175.0m—reflecting a 22.2% discount against its 2024 Red Book valuation of £225.0m—the offering combines immediate income generation with substantial planning-led capital upside.
Portfolio Composition and Asset Breakdown
The collection encompasses approximately 40 prime residential units, blending elegant period apartments with flexible mews properties across a sprawling footprint:
-
Block Group One comprises 8 units across 14,540 sq ft NSA on a block-schedule basis, generating a robust baseline rental income with established energy performance ratings.
-
Block Group Two features 6 flats spanning 8,413 sq ft NSA, holding immediate asset management upside through vacant refurbishment and consented lift installations.
-
Block Group Three encompasses 7 units including 6 flats and 1 mews house across 9,477 sq ft NSA, backed by live planning permissions for basement expansion and structural reconfiguration.
-
Block Group Four comprises 7 units across 6,684 sq ft NSA, featuring approved consents for basement and mansard extensions to drive long-term square footage growth.
-
Block Group Five is the largest block component with 8 units across 11,827 sq ft NSA, incorporating mews garage space and recent planning approvals for a luxury leisure suite and swimming pool.
Financial Metrics and Cost Structuring
Evaluating a portfolio of this magnitude requires rigorous financial modeling, particularly regarding entry yields and total capital expenditure. Based on the vendor's firm price of £175.0m, the baseline passing rent of approximately £5.09m p.a. delivers a gross yield of roughly 2.91%, which scales up to 3.97% against the vendor's un-reconciled rent roll of £6.95m.
When factoring in all transaction variables—including a 3% buyer's fee (£5.25m), estimated Stamp Duty Land Tax (SDLT), legal due diligence costs, and an anticipated seller-estimated capex program of £40.0m—the total all-in cost basis reaches approximately £230.5m. With post-works net saleable area projected to expand significantly through consented development, the portfolio is structured to achieve substantial gross value creation against anticipated post-completion gross development values (GDV).
Strategic Planning-Led Value Creation
Beyond passive rental yields, the portfolio derives significant intrinsic value from a series of active, planning-approved asset management initiatives across the blocks:
-
External lift integration introduces a modern passenger lift connecting the lower ground to upper floors, materially enhancing rental desirability and unit values.
-
Basement and mansard expansions allow for new basement digging, structural reconfigurations, and mansard roof additions, expanding net saleable floor areas.
-
Luxury leisure amenities permit the creation of an underground swimming pool, a dedicated leisure suite, and a full-width roof terrace, catering directly to ultra-prime tenant demands.
Corporate Structure and Transaction Protocol
The assets are securely held across two offshore special purpose vehicles (SPVs), allowing prospective buyers flexibility through either a direct asset purchase or a debt-free share transfer structure. Due to the highly confidential nature of this off-market offering, further data room access, tenancy schedules, and detailed legal documentation are strictly restricted.
In accordance with vendor instructions, data room credentials and comprehensive due diligence materials are released exclusively upon receipt of a signed Letter of Intent (LOI), valid Proof of Funds (POF), and verification of the purchaser's track record.
Advisor and Contact Details
For qualified institutional investors, family offices, and principal buyers seeking data room access or preliminary scoping discussions:
-
Submission Requirements: Signed Letter of Intent (LOI) & valid Proof of Funds (POF)
-
Deal Inquiries: Contact HPC Consultancy Ltd directly via email at hello@hpccc.co.uk or call the London office at +44 20 8191 0786 to connect with an AI strategist and secure data room credentials.
Frequently Asked Questions: Securing Prime London Real Estate Through Off-Market Freehold Aggregations for Croatia Investors
Section 1: Introduction to Off-Market Freehold Aggregations for Croatia Stakeholders
-
How can investors across Croatia access off-market prime London real estate opportunities?
Capital allocators located throughout Croatia can access confidential trophy assets by connecting directly with specialized advisory channels like HPC Consultancy Ltd to submit qualified proof of funds and secure data room credentials. -
Why is securing a controlling interest in a historic London square considered a rare opportunity for Croatia buyers?
Institutional-scale freehold aggregations across entire historic blocks in prime locations like Knightsbridge rarely come to open market, making off-market channels the primary avenue for buyers across Croatia. -
What makes prime central London real estate a resilient asset class for wealth managers across Croatia?
London maintains enduring global appeal for family offices throughout Croatia due to its legal transparency, political stability, historical capital preservation, and chronic undersupply of ultra-prime housing. -
What specific geographic enclave does this off-market freehold portfolio occupy for Croatia investors?
The portfolio is located within the Royal Borough of Kensington and Chelsea (RBKC), centered around premier addresses in Knightsbridge, London SW1X, offering exceptional prestige to buyers across Croatia. -
How does an off-market aggregation differ from buying individual residential apartments for Croatia principals?
Acquiring an entire freehold collection grants principals across Croatia structural control, unified management rights, and significant upside potential through comprehensive asset repositioning. -
What caliber of investor from Croatia is targeted for this specific £175m portfolio acquisition?
The offering is tailored for institutional investors, family offices, and high-net-worth principals across Croatia seeking high-value alternative real estate assets. -
How does the vendor-stated firm price compare against independent professional valuations for Croatia funds?
The vendor's firm price of £175.0m represents a 22.2% discount against the 2024 Red Book valuation of £225.0m, presenting an immediate valuation arbitrage opportunity for funds operating across Croatia. -
What is the approximate total scale and unit count of the portfolio available to Croatia syndicates?
The collection encompasses approximately 40 prime residential units spanning over 50,000 to 57,000 sq ft of net saleable area (NSA), readily accommodating large-scale syndicates from Croatia. -
Why do family offices from Croatia favor prime London residential freeholds over other asset classes?
Freehold tenures eliminate ground rent complexities and leasehold decay risks, providing ultimate long-term security and generational wealth preservation for investors across Croatia. -
How can interested principals throughout Croatia initiate preliminary acquisition discussions?
Parties across Croatia can contact HPC Consultancy Ltd directly via email at hello@hpccc.co.uk or call the London office at +44 20 8191 0786 to begin the qualification process.
Section 2: Portfolio Composition and Asset Breakdown for Croatia Portfolios
-
What specific assets are included within the six block groups of the collection for Croatia review?
The portfolio comprises six distinct freehold block groups on Cadogan Square alongside complementary mews houses on Pavilion Road, available for thorough inspection by buyers across Croatia. -
What are the key structural features of Block Group One for Croatia asset managers?
It comprises 8 units across 14,540 sq ft NSA on a block-schedule basis, generating a robust baseline rental income with established C-D energy performance ratings suitable for conservative portfolios across Croatia. -
What immediate value-add potential exists within Block Group Two for Croatia developers?
Featuring 6 flats spanning 8,413 sq ft NSA, this block holds immediate asset management upside through vacant apartment refurbishment and consented lift installations, attracting developers across Croatia. -
What planning permissions are attached to Block Group Three for Croatia planning strategists?
It encompasses 7 units (6 flats and 1 mews house) across 9,477 sq ft NSA, backed by live planning permissions for basement expansion and structural layout reconfiguration, analyzed closely by teams across Croatia. -
How does Block Group Four contribute to portfolio expansion for Croatia investors?
Comprising 7 units across 6,684 sq ft NSA, it features approved consents for basement excavation and mansard roof extensions to drive long-term square footage growth valued by buyers across Croatia. -
What major leisure amenities are approved for Block Group Five for Croatia luxury operators?
As the largest block component with 8 units across 11,827 sq ft NSA, it incorporates mews garage space and recent planning approvals for a luxury leisure suite and swimming pool, appealing to operators across Croatia. -
What is the current condition of the residential units across the portfolio for Croatia inspection?
The collection features a mix of fully let income-producing apartments and vacant units designated for comprehensive refurbishment and modernization evaluated by engineers across Croatia. -
Are floor plans and architectural diagrams available for review by Croatia technical teams?
Yes, comprehensive block-by-block floor plans, GIA/NSA schedules, and architectural drawings are released to qualified buyers across Croatia upon data room access. -
How do energy performance certificate (EPC) ratings impact the letting potential for Croatia landlords?
Units rated below EPC E must be upgraded before lawful letting, forming a key compliance task for landlords based across Croatia. -
Can individual blocks within the portfolio be acquired separately by Croatia purchasers?
While offered primarily as a single freehold aggregation, the vendor has occasionally indicated flexibility to consider partial disposals under specific terms negotiated by buyers across Croatia.
Section 3: Financial Metrics, Capital Structuring, and Costs for Croatia Capital
-
What is the precise financial breakdown of the entry price and headline costs for Croatia accountants?
The vendor's firm price is £175.0m, which sits alongside a 3% buyer's fee (£5.25m), estimated Stamp Duty Land Tax (SDLT), and legal due diligence costs modeled by financial planners across Croatia. -
What is the projected total capital expenditure (capex) required for Croatia financial sponsors?
The seller estimates an anticipated capex program of approximately £40.0m to execute full refurbishment and structural enhancement plans budgeted by sponsors across Croatia. -
What is the total all-in cost basis for an acquiring principal from Croatia?
When combining the purchase price, fees, tax estimates, legal costs, and capex, the total all-in cost basis reaches approximately £230.5m reviewed by investors across Croatia. -
What baseline passing rent does the portfolio currently generate for Croatia income seekers?
The current block-schedule passing rent stands at approximately £5.09m p.a., delivering a gross entry yield of roughly 2.91% tracked by funds across Croatia. -
How does the vendor-stated rent roll compare to the baseline schedule for Croatia analysts?
The vendor quotes an un-reconciled rent roll of £6.95m p.a. (reflecting a 36% premium over passing rent), which scales gross yields up to 3.97% examined by analysts across Croatia. -
What gross development value (GDV) is anticipated upon completion for Croatia equity partners?
The seller’s projected GDV reaches approximately £338.0m, implying substantial gross value creation for incoming equity partners from Croatia. -
How is Stamp Duty Land Tax (SDLT) calculated for a multi-dwelling freehold portfolio for Croatia tax advisors?
SDLT is estimated using specialized rules (such as the six-or-more-dwellings rule), though formal tax advice is essential depending on the acquisition structure managed by advisors across Croatia. -
Is debt leverage viable for financing this transaction for Croatia lending institutions?
On schedule passing rent, net yields on entry cost sit around 2.14%, meaning traditional leverage can be dilutive unless supported by rental growth or vendor-stated rent rolls assessed by lenders across Croatia. -
What gross sales costs are factored into financial sensitivity models by Croatia modelers?
Standard financial screening models apply a conservative 2% sales cost assumption before finance and tax calculations utilized by modelers across Croatia. -
What is the estimated break-even post-works value required for Croatia risk assessors?
Post-works value must reach approximately £235m (or roughly £4,351 psf on post-works NSA) to achieve financial break-even before finance costs evaluated by risk teams across Croatia.
Section 4: Planning-Led Value Creation and Asset Management for Croatia Operators
-
What drives the primary value-add upside across the six block groups for Croatia asset managers?
Value is unlocked through a combination of structural extensions, basement digging, lift installations, and interior modernizations executed by managers across Croatia. -
What specific upgrades are consented for 35 Cadogan Square for Croatia project leads?
Planning consent covers the installation of an external passenger lift from the lower ground to the third floor, adding direct lift access and a £300k rental uplift directed by project leads across Croatia. -
What structural expansions are approved for 39 Cadogan Square & 138 Pavilion Road for Croatia engineers?
Consents include the addition of a new lower ground basement level, internal layout reconfigurations, and fenestration amendments increasing GIA by ~689 sq ft supervised by engineers across Croatia. -
What are the details of the planning permission granted for 47 Cadogan Square for Croatia developers?
Approvals cover a basement level addition, a second-floor mansard with dormer windows, and rooftop plant enclosures expanding NSA by 661 sq ft leveraged by developers across Croatia. -
What major leisure features are authorized for 150 Pavilion Road for Croatia luxury brands?
Consents allow for a luxury leisure suite featuring an underground swimming pool, expanded GIA across four floors, and a full-width roof terrace utilized by brands across Croatia. -
How do planning implementation windows affect active consents for Croatia compliance teams?
Certain consents (such as 47 Cadogan Square) require verified proof of lawful implementation to prevent expiration within standard three-year windows audited by teams across Croatia. -
What immediate asset management steps can be taken prior to heavy capex works by Croatia landlords?
Immediate steps include re-letting vacant units, formalizing tenancy agreements, and executing light cosmetic upgrades on staff and storage rooms planned by landlords across Croatia. -
How does adding a passenger lift impact tenant demand in Knightsbridge for Croatia leasing agents?
Historic period conversions lacking elevators experience significant valuation discounts; adding modern lift access elevates rental yields to top-tier market standards noted by agents across Croatia. -
Who oversees the architectural and construction execution during the repositioning phase for Croatia owners?
A vendor-side in-house team can assist with planning delivery or provide a 6 to 12-month operational transition period for incoming owners from Croatia. -
How are quantity surveyor (QS) cost plans utilized during due diligence by Croatia consultants?
A detailed QS cost plan is recommended to verify that the estimated £40m capex budget accurately covers the extensive scope of works reviewed by consultants across Croatia.
Section 5: Transaction Protocol, SPV Structures, and Closing Steps for Croatia Buyers
-
How is the portfolio legally structured under current ownership for Croatia legal counsels?
The assets are held securely across two offshore Special Purpose Vehicles (SPVs), separating the block groups for streamlined corporate management vetted by legal counsels across Croatia. -
What transaction structure options are available to prospective buyers from Croatia?
Buyers can choose between a direct asset purchase (debt-free or debt-assumed) or an offshore share transfer of the SPV entities selected by buyers across Croatia. -
What are the primary advantages of an offshore share transfer structure for Croatia corporate groups?
Share transfers can offer alternative SDLT treatment, though inheriting entity history requires rigorous legal and tax due diligence undertaken by corporate groups across Croatia. -
What strict prerequisites are required to access the electronic data room for Croatia applicants?
Data room access requires an established track record of the principal buyer, a signed Letter of Intent (LOI), and valid Proof of Funds (POF) submitted by applicants across Croatia. -
What documentation must be submitted alongside a formal acquisition offer from Croatia principals?
Formal offers must be submitted on official company letterhead, detailing the purchase price, terms, exchange timeline, solicitor details, and source of funds provided by principals across Croatia. -
How is Anti-Money Laundering (AML) compliance handled for a £175m offshore transaction involving Croatia parties?
Rigorous source of wealth and source of funds checks are conducted on the purchasing principals and ultimate beneficial owners (UBOs) originating from Croatia. -
What buyer advisory fee applies upon successful completion for Croatia signatories?
A 3% buyer's fee (£5.25m) is payable by the purchaser to the advisory representatives upon formal completion acknowledged by signatories across Croatia. -
What is the typical timeline from initial LOI submission to final contract exchange for Croatia buyers?
Timelines vary based on data room review speed and legal due diligence, typically spanning several weeks of intensive coordination managed by buyers across Croatia. -
Are physical property inspections permitted during the due diligence phase for Croatia inspection teams?
Physical access and surveys can be arranged following successful qualification and data room admission coordinated for teams across Croatia. -
How can investors across Croatia immediately secure data room credentials for this opportunity?
Qualified principals located throughout Croatia can contact HPC Consultancy Ltd via email at hello@hpccc.co.uk or call +44 20 8191 0786 to submit their LOI and POF documentation.